
Banking Licences Demand Rigorous, Continuous Compliance. Central Bank Enforces Standards. Violations Cost Everything.
Central Bank UAE Compliance, Protect Depositor Funds or Forfeit Banking License
Every bank, finance company, and regulated financial institution in the UAE must comply with Central Bank regulations covering capital adequacy, liquidity, governance, risk management, and consumer protection. CBUAE violations trigger enforcement actions and license revocation. Reach compliance readiness faster with banking regulatory automation.
Reach CBUAE Compliance Readiness Fast
Protect depositors and maintain banking authorization
Central Bank supervises UAE's entire banking system.
The Central Bank of the UAE is the banking regulator and monetary authority for all UAE financial institutions outside financial free zones. CBUAE licenses and supervises commercial banks, Islamic banks, foreign bank branches, finance companies, exchange houses, payment service providers, and FinTech firms. Central Bank establishes prudential requirements: capital adequacy ratios aligned with Basel III, liquidity coverage ratios, corporate governance standards, risk management frameworks, AML/CTF programs, consumer protection rules, and operational resilience requirements. CBUAE conducts regular examinations assessing financial condition, risk management quality, compliance with regulations, and protection of depositor funds. Banking violations threaten financial stability, depositor confidence, and economic growth. Organizations treating Central Bank requirements as guidelines discover banking supervision is complete, enforcement is decisive, and license revocation ends financial services operations permanently.
Financial stability depends on banking compliance. Depositor protection is non-negotiable.
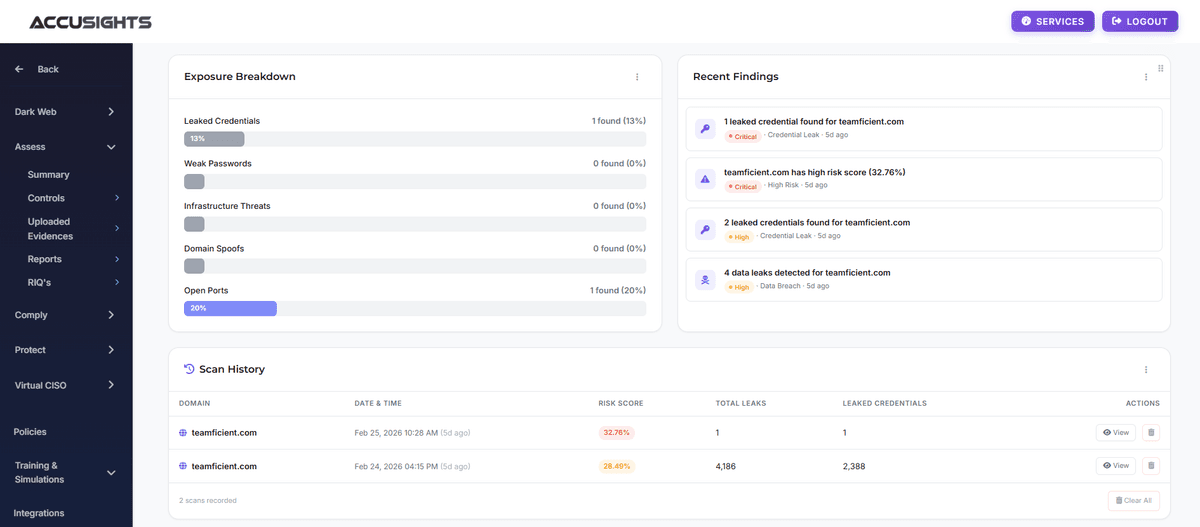
Evidence Basel III Capital Adequacy
CBUAE mandates capital adequacy ratios aligned with Basel III: Common Equity Tier 1 (CET1), Tier 1 capital, Total capital ratios, capital conservation buffers, and countercyclical buffers. Banks must maintain capital sufficient to absorb losses and continue operations during stress. Capital inadequacy triggers regulatory restrictions and threatens banking license. AccuSights maps the capital requirements that apply, assesses whether the governing policies and controls exist, assigns remediation and keeps the capital adequacy documentation CBUAE examines. Ratio calculation, risk-weighted asset tracking and capital forecasting stay with the bank and its finance systems.
Basel III alignment. Capital ratios. Buffer requirements.
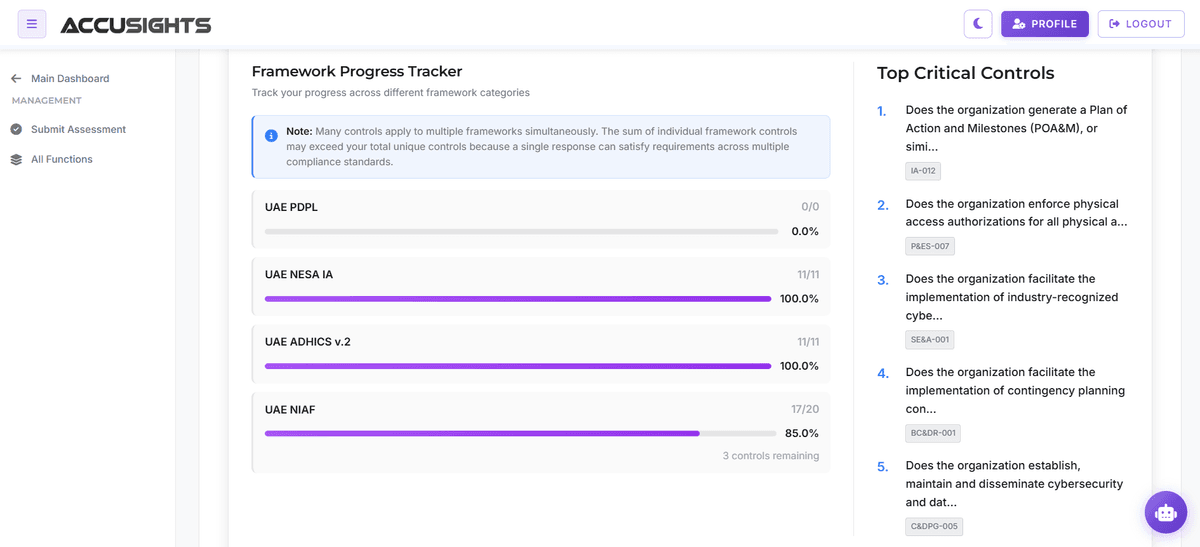
Evidence the Liquidity Coverage Requirements
CBUAE requires complete liquidity management: Liquidity Coverage Ratio (LCR), Net Stable Funding Ratio (NSFR), high-quality liquid assets, stress testing, contingency funding plans, and intraday liquidity monitoring. Banks must maintain liquidity sufficient to survive stress scenarios without central bank support. Liquidity failures cause bank runs and systemic crises. AccuSights maps the liquidity requirements, assesses whether the governing policies, stress-testing procedures and contingency plans exist, and keeps the liquidity documentation CBUAE compliance requires. The ratios, positions and stress tests are run by the bank.
LCR and NSFR compliance. Stress testing. Contingency planning.
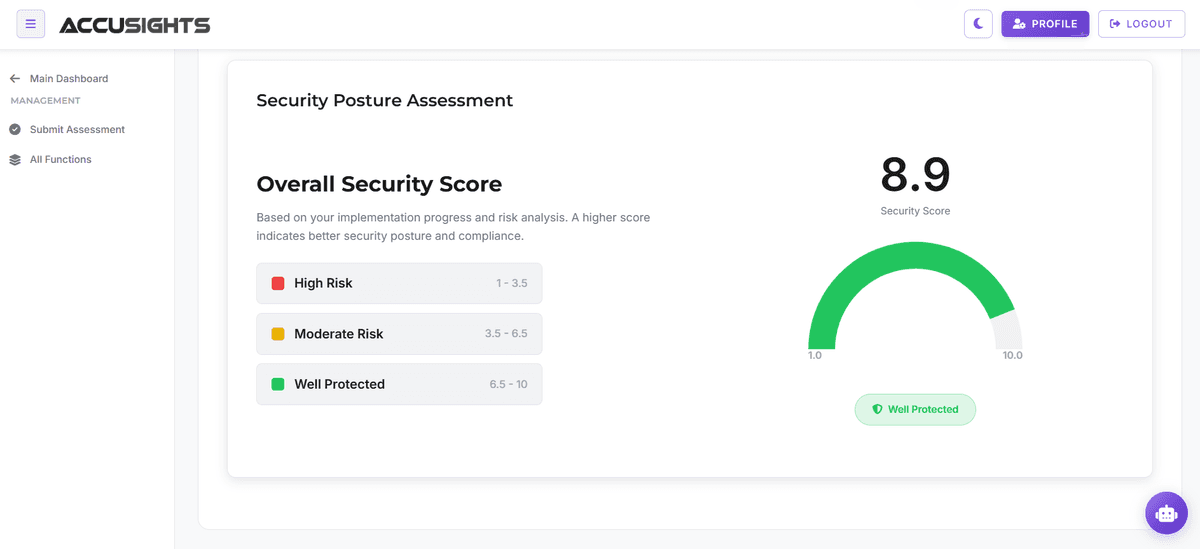
Strengthen Corporate Governance and Risk Management
CBUAE mandates strong governance and risk management: board composition and independence, board committees (audit, risk, nomination, remuneration), management structure, three lines of defense, enterprise risk management frameworks, risk appetite statements, and internal controls. Banks manage complex risks, credit, market, operational, liquidity, compliance, requiring sophisticated governance. Governance failures enable excessive risk-taking and threaten financial stability. We map the governance requirements to what you have, assess whether the board committees, mandates and risk framework are documented and current, assign remediation and link the evidence behind each answer.
Board oversight. Risk frameworks. Three lines of defense.
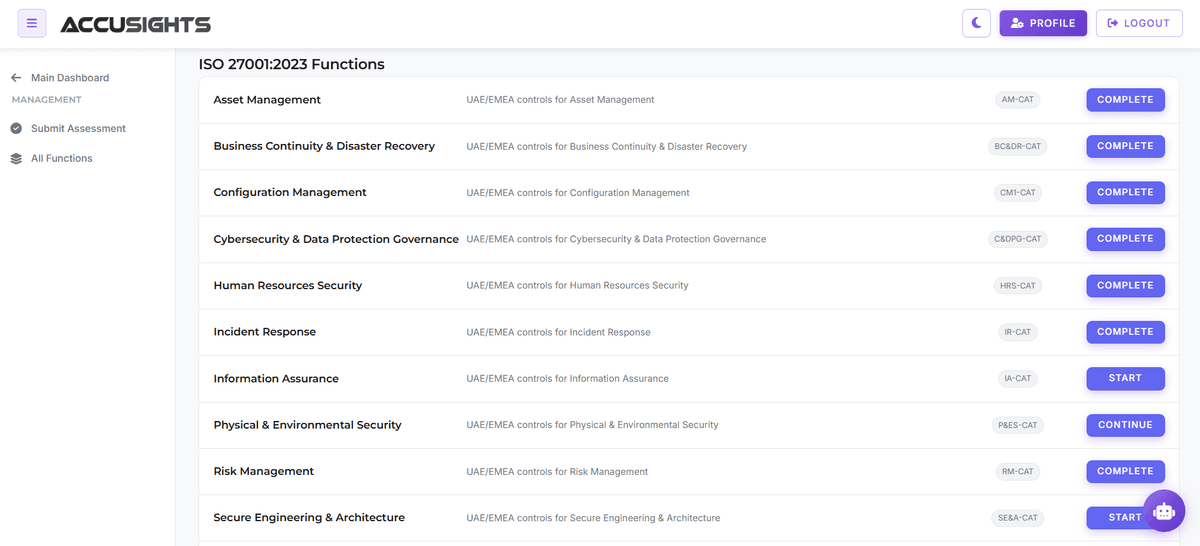
Implement CBUAE AML/CTF Requirements
CBUAE enforces complete AML/CTF programs aligned with UAE Federal Law and FATF standards: customer due diligence, enhanced due diligence for high-risk customers and PEPs, ongoing monitoring, sanctions screening against UNSC and local lists, suspicious transaction reporting to Financial Intelligence Unit, record keeping, and employee training. Banks are gatekeepers preventing financial crime. AML/CTF failures enable money laundering, terrorist financing, and sanctions violations. AccuSights maps the AML/CTF requirements, assesses whether the required policies and controls exist, assigns remediation and keeps the records CBUAE reviews. Due diligence, screening, transaction monitoring and suspicious transaction reports to the Financial Intelligence Unit are done by the bank.
AML/CTF requirements mapped. Control gaps assessed. Records kept.
Implement Consumer Protection Standards
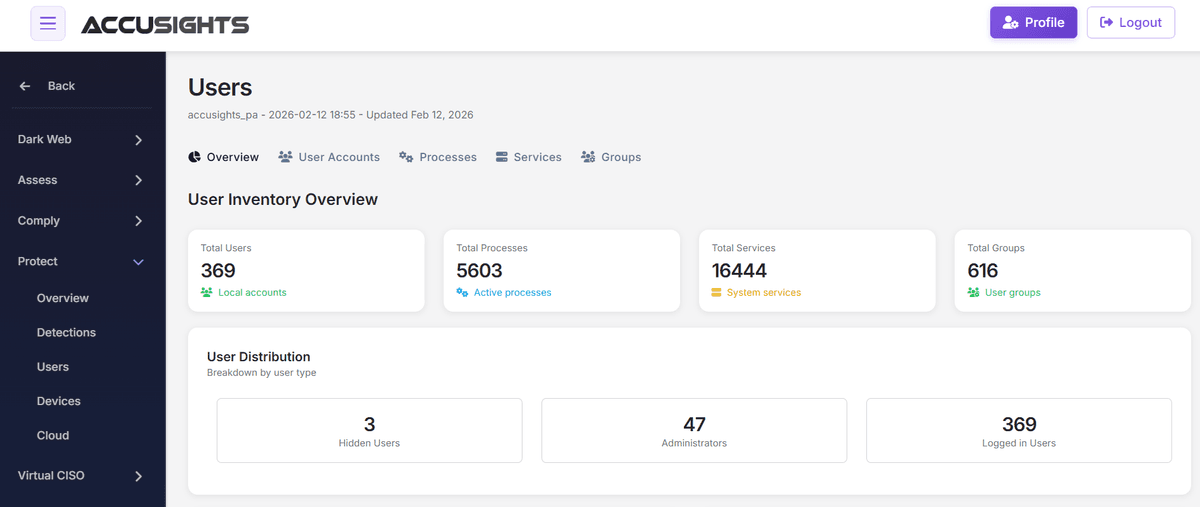
CBUAE requires complete consumer protection: transparent disclosure, fair treatment, suitable product recommendations, complaint handling procedures, dispute resolution mechanisms, financial literacy initiatives, and vulnerable customer protections. Banking customers deserve protection from unfair practices, hidden fees, and unsuitable products. Consumer protection failures damage reputation and trigger regulatory sanctions. We map the consumer protection standards that apply to you and assess whether the disclosure, complaints-handling and record-keeping controls exist. Handling the complaints themselves, and judging suitability for a customer, stay with the institution.
Transparent disclosure. Fair treatment. Complaint resolution.
Prepare for Central Bank Supervisory Examinations
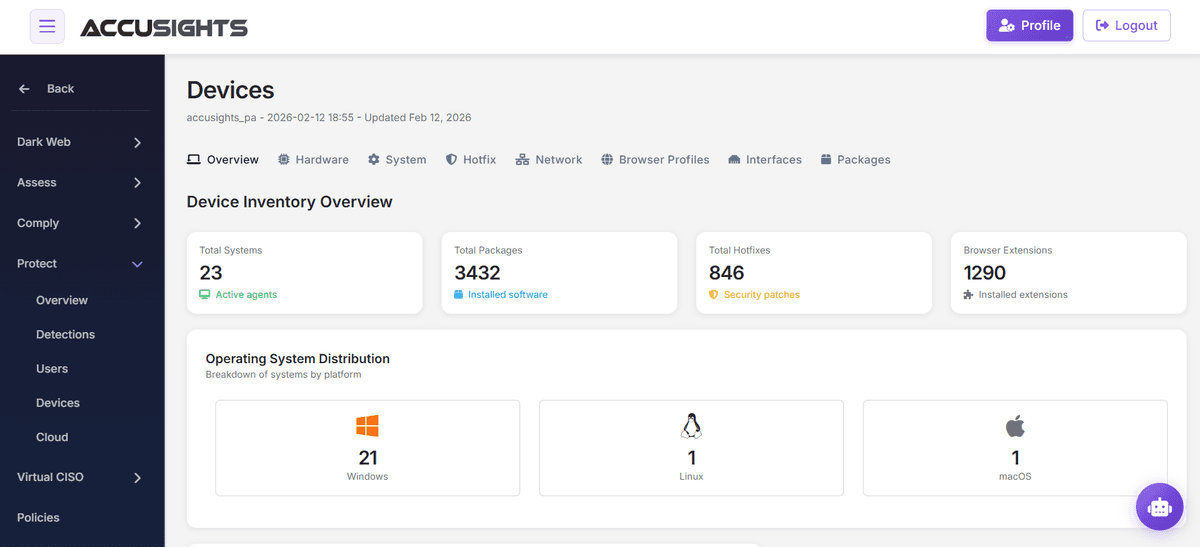
CBUAE conducts complete examinations assessing financial condition, capital adequacy, liquidity management, asset quality, earnings, management quality, governance effectiveness, risk management frameworks, AML/CTF programs, consumer protection, operational resilience, and regulatory compliance. Examinations determine supervisory ratings affecting capital requirements and growth authorization. Examination failures trigger enforcement actions including restrictions, fines, and license revocation. We keep the readiness record current between examinations, so what the supervisor asks for is a report you already hold rather than a scramble.
Always examination-ready. Complete documentation. Banking compliance.
Why Banks and Financial Institutions Choose This Path
From regulatory gaps to Central Bank compliance.
Organizations working with us:
Pass CBUAE Examinations
Complete implementation and documentation mean Central Bank examinations become routine supervision instead of license threats.
Prove Capital Adequacy
The Basel III capital requirements mapped to your licence, with the governing policies, controls and evidence tracked. Ratio calculation stays in your finance systems.
Prove Liquidity Management
The LCR, NSFR, stress-testing and contingency-funding requirements mapped, with the supporting policies and evidence tracked. The ratios themselves are run by the bank.
Strengthen Governance
Strong governance frameworks, board oversight, and risk management prevent excessive risk-taking and ensure stability.
Prove the AML/CTF Program
The FATF-aligned AML/CTF requirements mapped to your licence, with control gaps assessed and evidence kept. Detection, screening and reporting run in the bank's own systems.
Protect Depositors
Consumer protection standards, transparent disclosure, and fair treatment ensure customer confidence and regulatory compliance.
Built for Central Bank readiness and continuous banking compliance management.
Implement Complete CBUAE Banking Requirements
The Central Bank rulebook is wide. We map it, assess it and keep the record; we do not run it.
Central Bank of UAE regulations provide complete requirements across licensing, capital adequacy (Basel III), liquidity management (LCR, NSFR), corporate governance, risk management (credit, market, operational, liquidity), AML/CTF, consumer protection, operational resilience, cyber security, outsourcing, business continuity, Islamic banking (for Sharia-compliant institutions), and regulatory reporting. We map those requirements, assess whether the required policies and controls exist, assign remediation and keep the readiness record current for examination. Operational execution stays within the licensed institution and its specialist systems.
Complete requirements. Depositor protection. Full CBUAE compliance.
AccuSights maps applicable regulatory requirements, assesses whether the required policies and controls exist, assigns remediation, links supporting evidence and maintains readiness records. Operational execution remains within the licensed institution and its specialist systems.
CBUAE Regulatory Areas
Complete banking supervision